Explained in the order they happen. Work out what you can carry, get a lender on the phone, ask about the county's $10,000, then go and look at houses. Whichever step you are standing on when you ring, a licensed Pennsylvania lender who writes that kind of loan is the one who calls you back, usually the same business day.
Answered day and night, and no part of it goes anywhere near your credit file.
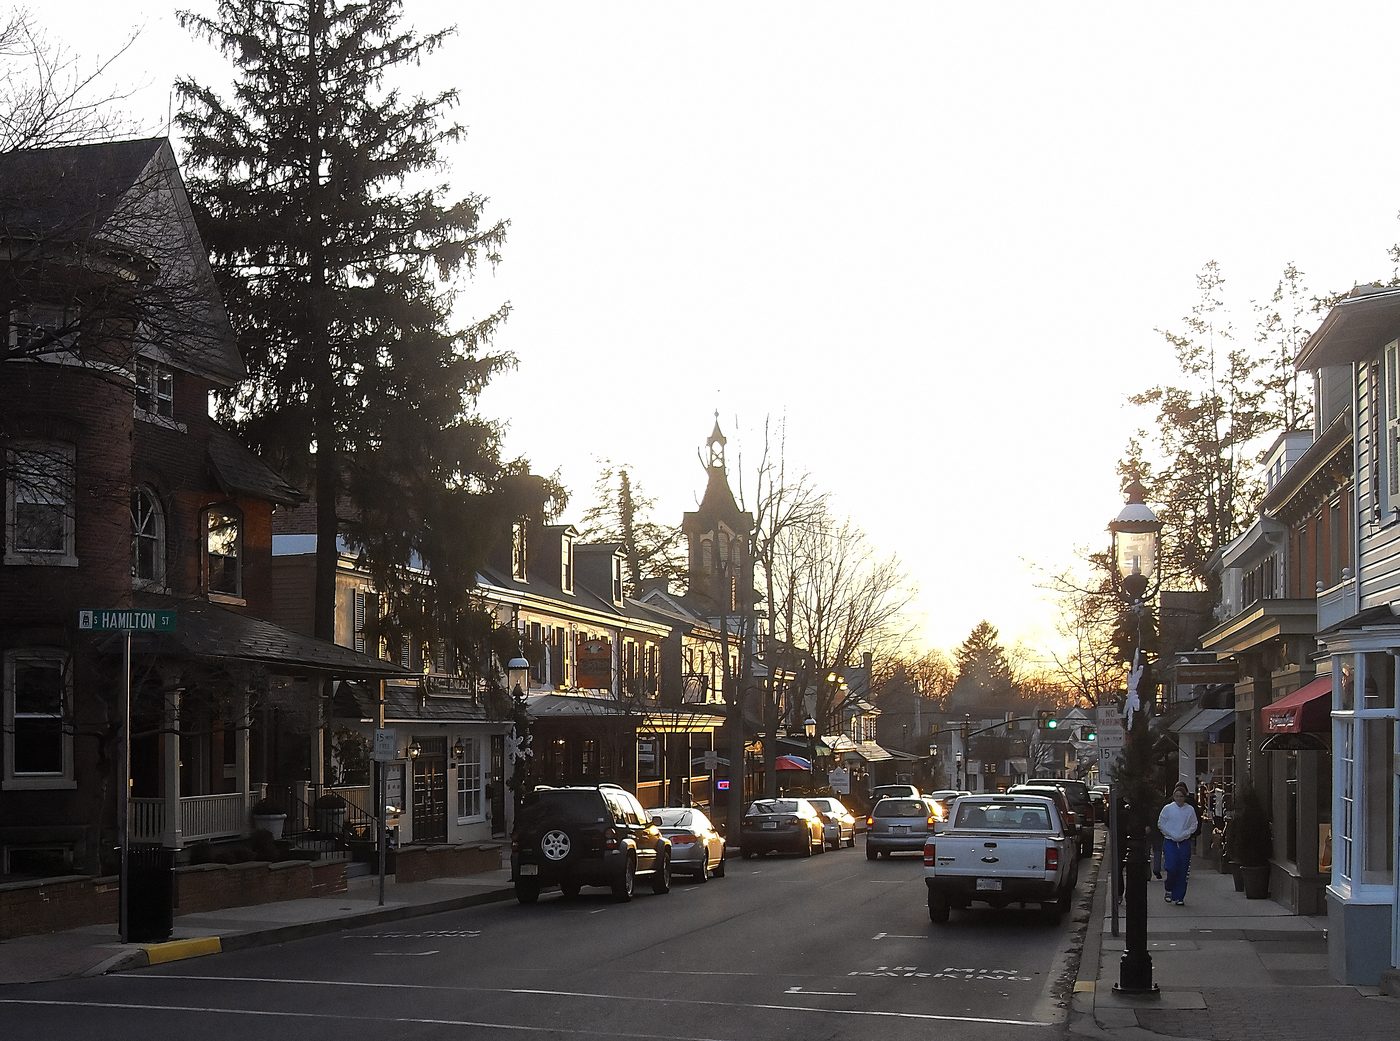
Bucks County. Downtown Doylestown late in the day. The county seat, where the recorder of deeds writes your name on the house at the end of all this. Photograph by Ekem, via Wikimedia Commons (CC BY-SA 3.0).
Every guide on this site is one of these steps, written all the way out.
The Bucks-only parts, one at a time
The 2% transfer tax and who pays it. The county's first-time buyer program and what it asks of you. Why a 1972 assessment is still on your tax bill and what the common level ratio does about it. What the Delaware does to a flood map in Morrisville, Bristol and New Hope. None of it is hard; nobody tells you the first time.
At any hour, and you are not put on hold. Whoever takes it writes it down, repeats the numbers back, and doesn't hurry you.
Buying or refinancing, which town, roughly what price, how soon, and whether this is your first house. Five minutes, no paperwork, no credit pull.
A licensed Pennsylvania lender who does that kind of loan, usually the same business day. Quotes, pre-approval and closing all happen there. We answer the phone and stay out of your paperwork.
Why this site is only about one county
They need to know that the transfer tax here is 2%, that half of it is customarily theirs, that the assessment on the bill is a 1972 number, and that the county has $10,000 sitting there at 0% for a first house. That is what is written out on these pages, one Bucks town at a time.
Lower county, central and up-county
Twelve towns and the county page, each with its own numbers: what a house goes for, which school district's millage is on the bill, and what to ask before you write an offer there. Route 611 at five o'clock is on none of them, which is the only mercy it offers.

FHA at 3.5% down, conventional at 3%, PHFA's Keystone loans, VA for anyone who served, USDA in the up-county pockets that still qualify. The published 2026 FHA limit for a single home here is $630,200, confirmed by the lender before it counts; conforming loans run to $832,750. Each page has the local catch, and the phone number gets answered.
No. Nothing on this site or this phone line touches your credit. A credit check happens later, and only once you decide to apply.
The same thing that happens at two in the afternoon. The line gets answered, you go through the same ten questions, and a licensed Pennsylvania lender follows up. No voicemail, no menu, no queue. What it will and won't do is written out here.
Call and say where it is. A Pennsylvania license covers the whole state, so Montgomery County, Philadelphia and everywhere else are the same phone call. The reason every page here is written for a Bucks town and a Bucks tax bill is that the numbers change at the line — the 1972 assessments, the county's $10,000, the school millage — and a page written for the wrong county is worse than no page. So the pages are Bucks. The phone is not.
2% of the sale price: 1% to Pennsylvania and 1% local. Buyer and seller customarily split it down the middle, so on a $400,000 house each side brings $4,000 to the closing table. A refinance owes none of it.
Say the town and roughly the price. The rest happens in order, and a licensed Pennsylvania lender walks you through each step of it.
(267) 828-9047About a minute of typing. We read it, and a licensed Pennsylvania lender who does this kind of loan calls you back, usually the same business day. Nothing here touches your credit. If you'd rather talk it through, the number is (267) 828-9047.
Sending this form asks a licensed Pennsylvania mortgage lender to get in touch with you about financing a home. It is a request for a call and nothing more: no loan application, no credit pull, nothing that shows up on your credit report. Bucks County PA, Home Loans is a marketing and referral service and is not a mortgage lender or broker. What happens when you call.
Somebody here reads it through and works out which kind of loan you have described.
A licensed Pennsylvania lender calls you, usually the same business day.
If the day after goes by with nobody calling, ring (267) 828-9047 and we'll chase it down.
If you'd rather talk now than wait for any of that, the same number works.